Banking Setbacks, Replanting Capital: A Measured UK Guide to Loss Harvesting
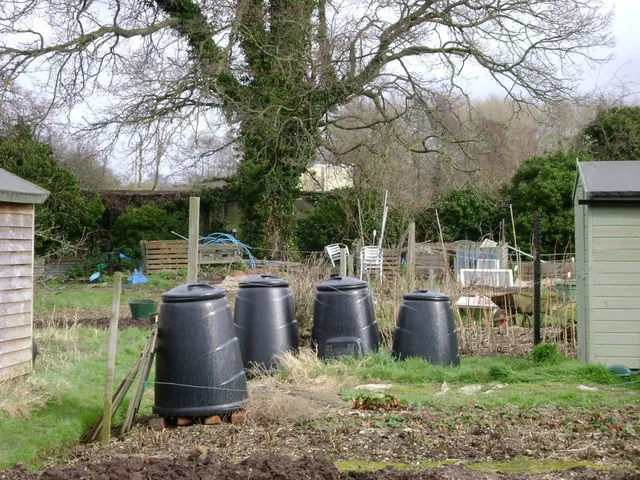
Photo: Robin Stott , CC BY-SA 2.0, via Wikimedia Commons
A compost heap is not glamorous. It is where prunings, peelings and spent growth are left to break down into something useful. A portfolio loss can work in a similar way. Realising a loss does not create value by itself, but within the UK capital gains tax rules it can be banked, offset against gains and carried forward for future use. The skill is in knowing what to compost, what to leave alone and when the tax tail is wagging the investment dog.
Why a loss can be an asset
For UK investors, a chargeable loss on a taxable investment can be set against chargeable gains in the same tax year. If the loss exceeds those gains, the unused amount can generally be carried forward and set against future gains. It cannot normally be offset against income.
For 2026/27, the capital gains tax annual exempt amount for individuals is £3,000. That exempt amount reduces the gains on which tax is due, but it does not make loss harvesting pointless. A realised loss can still protect gains above the exempt amount, and unused losses can be stored for later years.
The important discipline is that losses must be claimed. They do not always flow automatically into a tax return. Records need to support the claim, and time limits apply. A loss that is never notified may be a missed planning opportunity.
The 30-day rule and bed-and-breakfast
The best-known trap is the bed-and-breakfast rule. Broadly, if you sell shares or securities at a loss and acquire the same or substantially identical shares within 30 days, the loss may be reduced or denied because the disposal is matched with the new purchase. The rule is intended to stop investors from crystallising a tax loss while remaining economically exposed to the same asset.
For many investors, the simplest response is to wait at least 31 days before repurchasing. That preserves the tax loss, but it also means time out of the market. A different holding may maintain exposure, but it must not be substantially identical, and it may change the portfolio's risk profile. Neither route should be chosen without weighing the investment case.
The rule can also catch repurchases made in an ISA or by a spouse or civil partner in some circumstances. Transfers between spouses and civil partners can be made without a gain or loss, but the interaction with the 30-day rule and anti-avoidance rules needs care. This is an area where advice is often worth taking before acting.
ISA versus taxable accounts
An ISA is a tax shelter. Gains and losses inside it have no capital gains tax consequence, so there is no loss to bank for use outside the ISA. Loss harvesting therefore belongs in a taxable account, where disposals can create allowable losses.
That distinction matters when investors hold the same fund in both an ISA and a dealing account. Selling in the taxable account may create a useful loss, but repurchasing the same holding in the ISA within 30 days can complicate the position. The sequencing needs to be checked rather than assumed.
For many households, the cleaner approach is to keep the tax-harvesting exercise inside the taxable portfolio and leave ISA holdings undisturbed. The ISA's role is to shelter future growth, not to generate losses for offset elsewhere.
Record-keeping is part of the strategy
Loss harvesting is only as good as the paper trail behind it. Keep contract notes, dates, amounts, fees and records of corporate actions. For shares, the UK matching rules mean disposals are matched with same-day acquisitions first, then acquisitions in the following 30 days, then the Section 104 pool. Funds and other securities can have their own complexities. A loss claim needs to be supported by evidence, not memory.
It is also worth keeping a simple log of losses claimed and losses carried forward. That helps when future gains arise and makes the annual tax return less reliant on reconstruction.
The risks of letting tax drive the decision
A tax saving is not an investment return. It is a reduction in a future tax bill, and it can be outweighed by the cost of achieving it. Dealing charges, bid-offer spreads, platform fees and stamp duty on UK shares can consume much of the benefit. Selling out of the market for 31 days introduces the risk that the asset moves before repurchase.
There is a deeper risk too. An investor who sells a sound long-term holding merely to bank a loss may end up with a worse portfolio and a modest tax credit. Tax planning should support the investment plan, not replace it. The compost heap works only if the material is genuinely spent; not every fallen leaf needs to be saved.
A practical sequence
- Identify realised gains and losses in the taxable portfolio before the end of the tax year.
- Check whether any loss-making disposal would be caught by the 30-day rule.
- Compare the likely tax saving with dealing costs, spreads and the risk of being out of the market.
- Consider whether a replacement holding preserves the investment exposure without being substantially identical.
- Execute deliberately, not in a year-end rush.
- Record the transaction and claim the loss within the relevant time limit.
- Carry forward unused losses and review them when future gains arise.
Loss harvesting is a housekeeping task, not a strategy in itself. Used with restraint, it can turn a setback into a stored allowance for future gains. Used carelessly, it can become an expensive exercise in letting tax dictate the portfolio. The measured approach is to bank the loss, keep the investment case in view and replant only when the ground is ready.